By Elena Petrova · Research Writer
Published
Answer in brief
Liability covers damage to others, so the price depends on how likely you are to cause a crash—record, age, location, credit, mileage—not on what your car is worth. A young urban driver can pay more for minimum coverage on a $2,000 car than a suburban 45-year-old pays for full coverage on a new one.
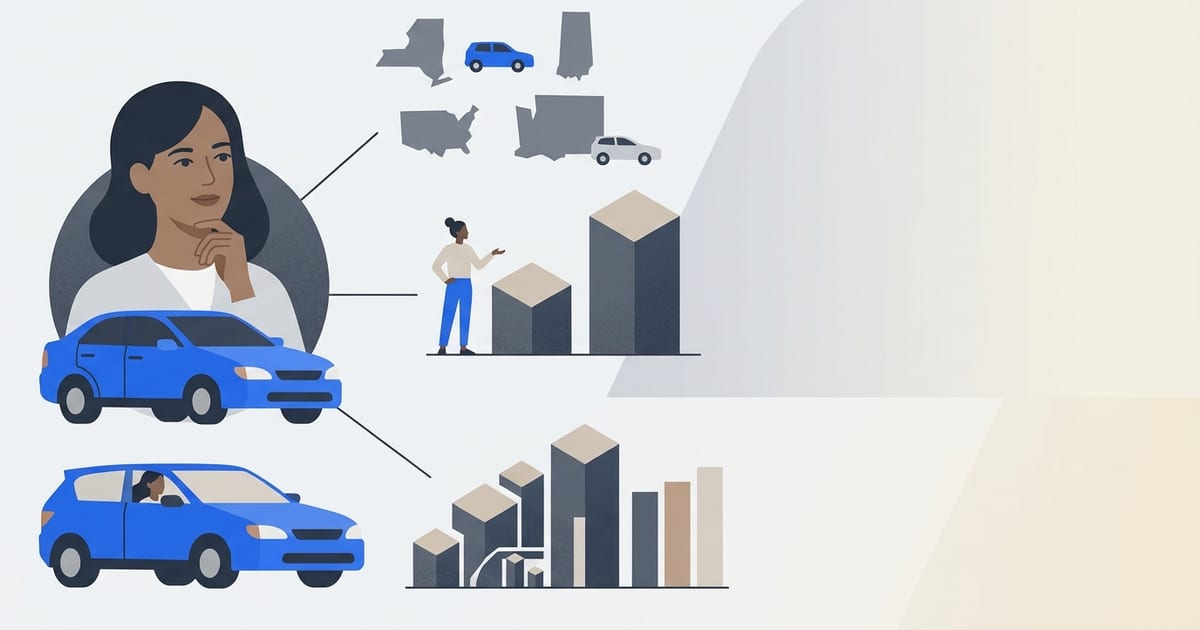
A reader with a $2,000 car was surprised that liability-only quotes came in at $1,800 a year. The surprise comes from a reasonable but wrong assumption: that cheap car means cheap insurance.
What liability prices
Liability pays for the other party's injuries and property. The car you drive barely affects how much damage you do to them; who you are and where you drive affects how often. So the factors are driver-centred: record, age, years licensed, ZIP code, credit-based score in most states, and mileage. The vehicle enters mainly through its weight and its liability loss history.
What this means
For a driver whose premium is high for driver reasons, the car is not the lever. Comparing insurers is—because they weight those driver factors differently—and so are time, a clean record, and the discounts in the cost guide.
Guides referenced in this post
Guide
How Much Liability-Only Car Insurance Costs
Typical liability-only premiums by state and driver, how much cheaper it is than full coverage, and why the saving is smaller than people expect at higher limits.
Guide
How to Compare Liability-Only Car Insurance Quotes
A method for comparing liability-only quotes: fix the limits, include UM and any required PIP, standardise inputs, add fees, and check for filings if needed.